Daily Market Letter: September 22, 2026
Archived sample · September 2026. Market conditions have changed since this was written; it's shown as an example of the letter's format, not current commentary.
Photo: USDA NRCS / Carly Whitmore
Market outlook Corn outlook: Erratic Soybeans outlook: Erratic
Corn
Market Outlook: Erratic
CBOT grains markets all rallied in unison yesterday following Sec Bessent’s comments about positive trade talks with China. And that is all it took…the market ran with the idea China will be here to buy $17 billion of US ag goods. This is much like the old Johnny Carson show where Ed McMahon would announce: Here comes Johnny. Well, what the market heard was Scott Bessent announcing: Here comes China. But, this is a politician being vaguely positive. And let’s be honest, we really have no clue what the end result will be. But, that does not stop a market from shooting first and asking questions later. But, I find it interesting that export cash markets were not firmer yesterday. If China was actually coming to buy corn soon, then basis at New Orleans and the PNW would be firmer. And basis yesterday was steady to lower. So, this was hugely speculators buying more corn futures contracts, at least 25,000 contracts yesterday. Meanwhile, US corn exports last week were massive at 76 million bushels, 30% larger than early September last year. As for crop progress, the US corn crop is now 92% dented, 58% mature, and 13% harvested, all just slightly ahead of normal. We still have a few scattered corn yields coming in thus far from farmer reports and seed company trials. But, in the next 1-2 weeks, we should be getting lots more yields and have a decent indication if the crop is actually getting smaller or not. As for the rest of this week, it looks like Chinese news will be the major driver, and that is anyone’s guess how that ends up.
Soybeans
Market Outlook: Erratic
CBOT soybeans started the week strong with optimism on China. Again, we really don’t know how this will end. Hopefully we are smarter on Friday. I had stated last week that China had bought 12 million tons and this was close to fulfilling its agreement from last October. I was wrong, the agreed amount last October was 25 million tons. So, China has more to go. So, that means that if China does make an agreement to buy US ags, that agreement likely means other ag items, likely not soybeans. As for US soybean exports last week, China was 60% of the tonnage. At current high prices, US soybean export demand is getting smaller, not bigger. As for the US crop progress, 62% of the crop is dropping leaves, and 12% is harvested. The soybean crop is progressing ahead of normal across the Midsouth and in the western and north western Corn Belt. Other areas are normal to behind a little bit. As for the US soybean condition rating, it was unchanged. Typically, late in the season, the soybean rating declines. This year, it has been unchanged the 5 weeks. Historically, this has meant the crop yield is NOT getting smaller. So, longer term, if the US yield is not lower, and crops are ok in S America, the world will have too many soybeans. Today, the market does not care about this at all. But, longer term, it is beginning to look like rallies are to be sold.
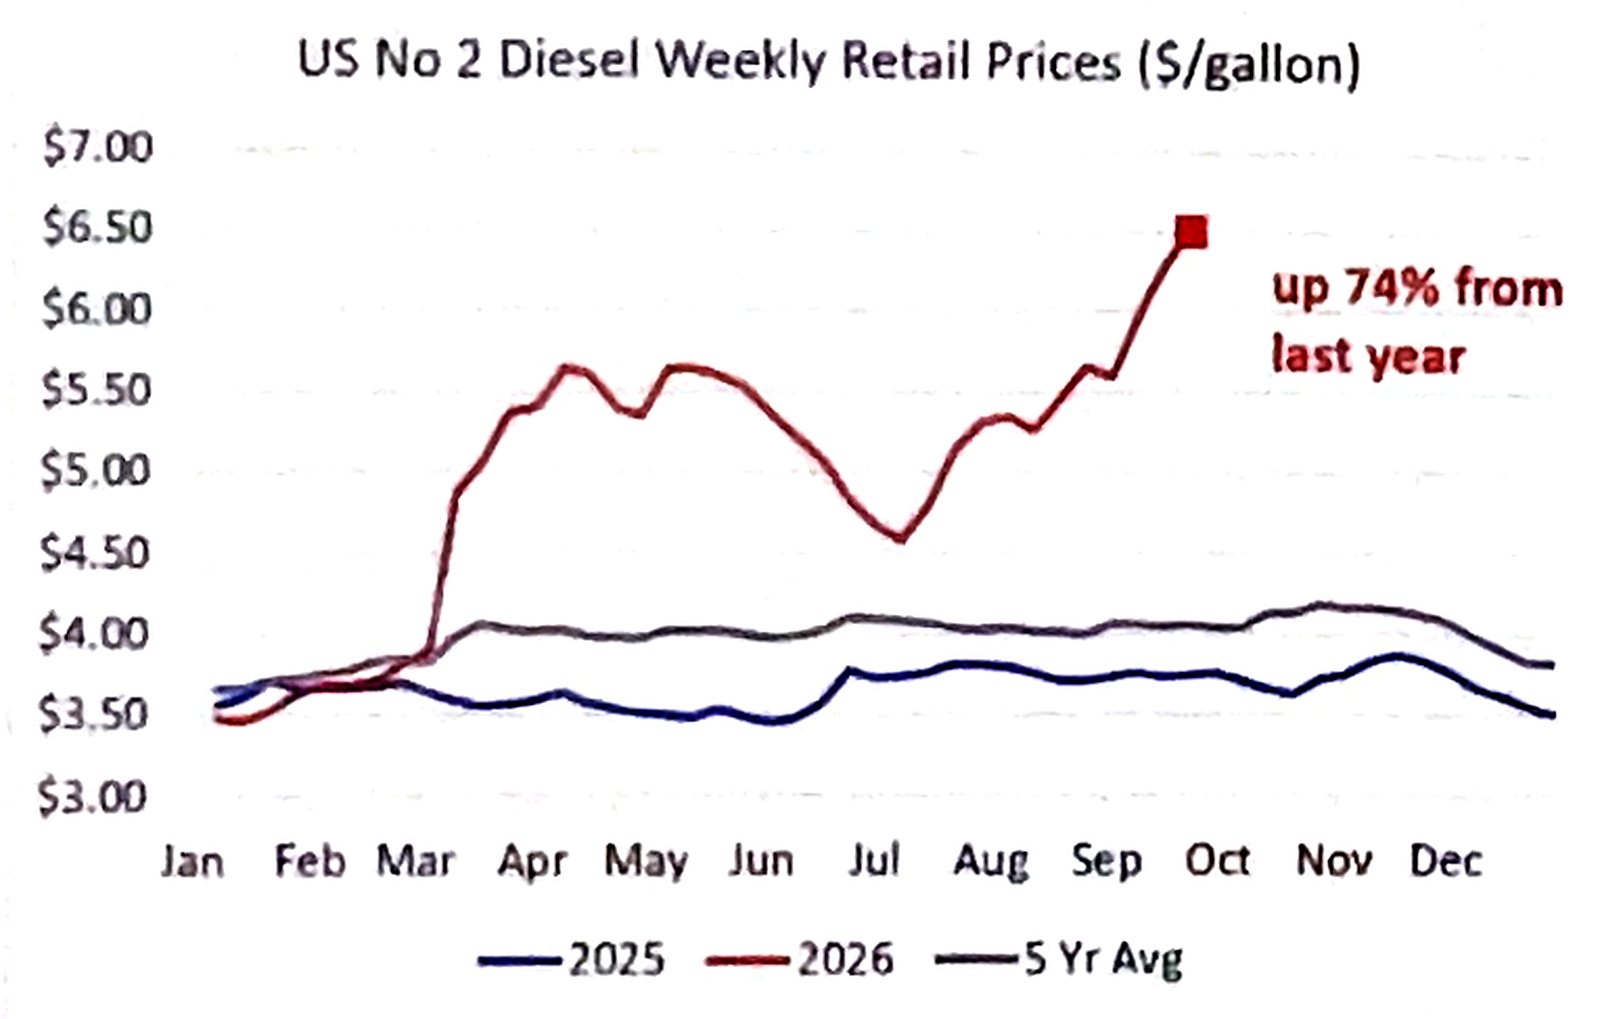
Chart of the day: US Diesel; Prices
Weather
The subscriber edition of this letter includes three precipitation forecast maps: US Ag Belt 1-5 Day Precip Forecast, US Ag Belt 6-10 Day Precip Forecast and S America 1-10 Day Precip Forecast. Chris’s notes on the South America map:
Central Brazil is still DRY, this needs to change!
And the main Grain Belt in Argentina could use more rains also.
Chris Myers
M6 Capital Management, LLC
Germantown, TN
Published in full with permission as an archived sample. Subscriber editions are licensed to the recipient only and may not be forwarded or redistributed.
Interested in the daily letter? Ask Chris about joining